Instant Bank Transfer Fees: When Paying for Seconds Is Worth It
Table of Contents
01 Event
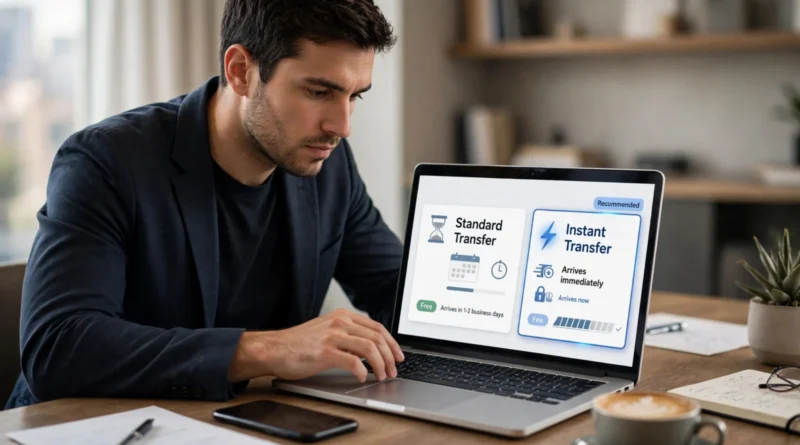
Instant bank transfers are becoming more common as financial institutions connect to faster payment systems that can move money in seconds, 24 hours a day. That creates a new consumer choice: wait for a slower transfer or pay for immediate availability.
02 What Changed?
The technology underneath an instant payment can be extremely inexpensive at the network level, but that does not mean the customer-facing service is always free. Banks and payment providers decide how they package instant transfers, whether they charge senders, and what transfer limits apply.
In the United States, the Federal Reserve’s FedNow Service allows participating institutions to send and receive payments within seconds around the clock. The Federal Reserve’s 2026 fee schedule lists a very small per-item network charge for standard customer credit transfers, illustrating that a bank’s retail fee can reflect much more than the raw network cost.
03 Why It Matters
Speed has value only when delay has a cost. Paying $5 to move $50 instantly is a 10% transaction cost. Paying $5 to move $5,000 when a same-day deadline prevents a late fee may be easy to justify.
Instant payments also reduce the time available to catch mistakes. If you send money to the wrong person or respond to a scam, the speed that made the transfer convenient can also make recovery more difficult.
04 What It Means for You
Before choosing instant delivery, ask what happens if you wait. If standard ACH will arrive tomorrow and there is no penalty for waiting, the instant fee may buy very little. If rent, a bill, or an urgent transfer must arrive immediately, the fee can be rational.
Confirm the recipient details carefully before sending. Unlike a slow transfer that may remain pending for some time, an instant payment can reach the receiving institution within seconds.
05 Numbers + Context
The Federal Reserve’s 2026 FedNow fee schedule lists a $0.045 customer credit transfer origination fee at the network level, while banks remain free to set their own customer pricing. That gap is a useful reminder: the retail price you see may include convenience, product positioning, fraud controls, support, and margin—not just payment-rail cost.
References: Federal Reserve Financial Services — FedNow Participants and Service; Federal Reserve Financial Services — 2026 FedNow Fee Schedule.
06 Earnyx Takeaway
Instant transfer fees are a price on urgency. Do not pay them automatically just because the option is highlighted. Compare the fee with the actual cost of waiting. When seconds matter, instant payment can be valuable. When they do not, standard transfer speed may be the better deal.