SB Energy Slows IPO as Investors Question the Economics of the AI Infrastructure Boom
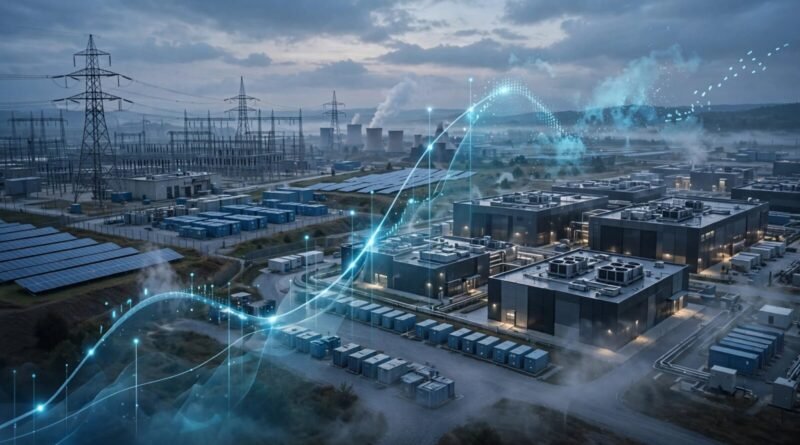
SoftBank-backed SB Energy is slowing plans for an initial public offering as investors take a harder look at the economics of the artificial-intelligence infrastructure boom.
Reuters reported on September 22 that the data-center and energy company is facing a tougher financing environment as investors question the enormous capital requirements behind future AI capacity. The development does not mean demand for AI infrastructure has disappeared. It shows that financing that infrastructure is becoming more selective.
The distinction matters. Technology companies can have strong demand for compute while individual infrastructure projects still struggle to produce attractive returns.
Table of Contents
Why AI infrastructure requires so much capital
A large AI campus needs far more than servers. Developers must secure land, grid connections, substations, cooling systems, backup power, networking and buildings before accelerators can begin generating revenue.
Many of those costs arrive years before a facility reaches full utilization. Developers therefore rely on debt, equity and long-term customer commitments to finance construction.
When interest rates or investor risk tolerance change, projects can become harder to fund even if expected demand remains high.
Data-center economics depend on utilization
A data center is most valuable when expensive infrastructure stays heavily utilized. Empty capacity still incurs financing, maintenance and energy-related costs.
That creates a forecasting challenge. Developers need to build ahead of demand because construction takes years, but building too far ahead can leave capital stranded.
AI makes the problem harder because technology changes quickly. A facility designed around one generation of hardware may need upgrades for higher power density or different cooling requirements when the next generation arrives.
Debt can amplify both returns and risks
Infrastructure developers often use debt because long-lived assets can support predictable cash flows. Borrowing can improve equity returns when projects perform as expected.
But leverage also creates fixed obligations. Interest and principal payments continue even if construction is delayed or customers use less capacity than forecast.
That is why investors increasingly focus on contracted revenue, creditworthy tenants and the terms under which customers commit to capacity.
The AI boom is entering a financial discipline phase
The first years of the generative-AI boom rewarded companies simply for demonstrating access to scarce compute. As supply expands, investors are asking harder questions: Who will use the capacity? At what price? For how long? And what return will the project earn after power, financing and equipment costs?
Those questions do not undermine the AI growth story. They are a normal part of a market moving from scarcity-driven expansion toward more mature capital allocation.
Projects with strong customers and favorable power arrangements may continue to attract financing, while speculative developments face more scrutiny.
Power access can be more valuable than the building
In many markets, the most difficult asset to secure is not land or construction capacity but electricity. Grid interconnection queues can stretch for years.
A site with a confirmed large power allocation can therefore have strategic value before a data center is built. Conversely, a project without reliable power may struggle to attract tenants regardless of its location.
This is one reason energy companies and data-center developers are becoming increasingly intertwined.
SoftBank’s broader AI strategy raises the stakes
SoftBank has positioned artificial intelligence as a central investment theme, backing infrastructure and technology companies across the ecosystem. SB Energy sits close to the intersection of power and computing that is becoming increasingly important for AI.
Slower IPO timing can give a company more opportunity to demonstrate contracted demand and improve market conditions. It can also signal that public investors are demanding stronger evidence before assigning aggressive valuations.
What this means for the data-center boom
A tougher IPO market could push developers toward private capital, joint ventures or project-level financing. Large technology companies may also become more directly involved in funding infrastructure if they need guaranteed capacity.
Consolidation is another possibility. Companies with strong balance sheets can acquire projects from developers that struggle to finance construction.
The result could be an AI infrastructure market that remains large but becomes more concentrated among operators with access to cheap capital and long-term customers.
What to watch next
For SB Energy, watch whether the IPO is rescheduled and what financial disclosures emerge when the process resumes. Contracted data-center capacity, debt levels and capital expenditure commitments will be especially important.
Across the industry, monitor financing costs and the gap between announced projects and facilities that actually reach construction. Headline gigawatts can overstate future supply when projects lack power or funding.
Customer concentration also matters. A data center dependent on one AI company can have strong revenue visibility but significant counterparty risk.
Bottom line
SB Energy’s slower IPO process is a reminder that the AI infrastructure boom has two sides. Demand for compute can grow rapidly while the capital required to build that compute becomes more expensive and harder to justify.
The next phase of the market will reward projects that combine power access, committed customers and disciplined financing. AI may continue to drive enormous infrastructure investment, but investors are increasingly asking whether each project can turn that demand into durable cash flow rather than simply participating in the boom.