ACH Transfer Fees and Limits: Why “Free” Bank Transfers Still Have Rules
Table of Contents
01 Event
ACH transfers are one of the most common ways money moves between U.S. bank accounts. Payroll, bill payments, mortgage drafts, and many bank-to-bank transfers use the Automated Clearing House network because it is efficient and usually inexpensive.
02 What Changed?
For consumers, an ACH transfer may appear to be simply “free bank transfer.” In practice, your bank can still control how much you may send, how quickly it is processed, whether same-day service is available, and whether fees apply to specific transfer types.
Those limits are often account-level policies rather than limits of the ACH network itself. A bank might cap outbound transfers per day or month, hold newly linked accounts, or require extra verification before large transfers.
03 Why It Matters
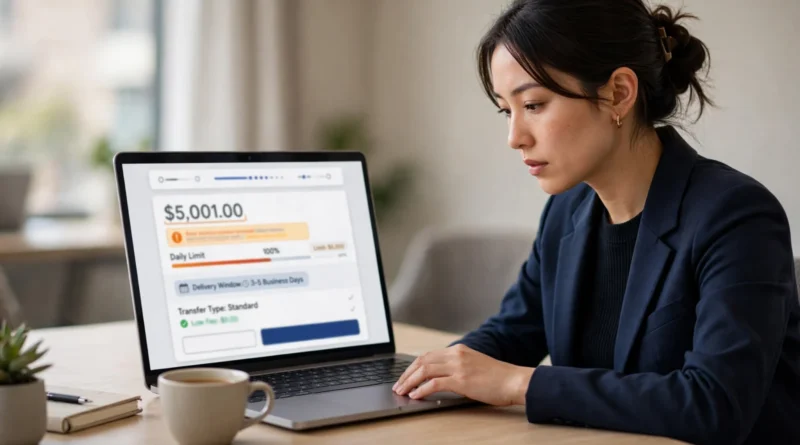
The difference between “ACH is cheap” and “ACH is suitable” becomes obvious when the payment is large or time-sensitive. If your bank allows only $5,000 per day and you need to move $20,000, a free transfer may take several days even if the recipient is ready immediately.
Limits can also affect emergency funding, down payments, investment transfers, or moving money between savings accounts. A fee-free method is not automatically the best method if the timing creates another cost.
04 What It Means for You
Before relying on ACH, check the sending limit, receiving limit, daily and monthly caps, expected settlement time, and whether the bank charges for expedited or same-day service. Also ask whether the limit changes after the external account has been verified for a certain period.
For routine transfers, ACH is often an excellent default. For very large or urgent transfers, compare it with a wire or instant-payment option instead of discovering the limit on the day money must move.
05 Numbers + Context
Suppose your bank allows $5,000 of outbound ACH transfers per day and you need to move $15,000. Even with no transfer fee, the limit can turn one transaction into three days of transfers. If a deadline matters, the economic cost is the delay—not the posted fee.
Financial institutions are required to disclose transaction limitations on deposit accounts, including limits on the number or dollar amount of certain withdrawals or transfers.
Reference: Consumer Financial Protection Bureau — Account Disclosures and Transaction Limitations.
06 Earnyx Takeaway
ACH is usually valuable because it is low-cost, not because it is unlimited. Know your bank’s transfer caps and timing rules before the day you need to move a large amount. A free transfer that misses the deadline can be more expensive than a paid transfer that arrives when required.