Emergency Travel Funds: How Much Backup Money Should You Bring?
Table of Contents
01 Event
Trips rarely go exactly as planned. A delayed flight can force an extra hotel night. A lost wallet can leave a traveler without access to cash. A minor medical issue can require an upfront payment. A missed connection can mean buying another ticket at the worst possible moment. These situations are inconvenient, but they become much more serious when the traveler has no financial buffer.
An emergency travel fund is money kept separate from normal vacation spending. Its purpose is not to make the trip more luxurious. It is to make sure one unexpected event does not force the traveler into expensive debt, unsafe choices or a premature trip home.
02 What Changed?
Modern travel relies heavily on cards, apps and digital bookings. That makes paying easier when everything works, but it also creates single points of failure. A frozen card, lost phone, account lockout or weak internet connection can temporarily cut off access to money. At the same time, travel disruptions can produce costs that must be paid immediately before reimbursement is possible.
Airlines and insurers may reimburse some expenses after a disruption, but reimbursement is not the same as having money available now. A traveler may still need to pay for a room, meal, taxi or replacement ticket first and submit a claim later.
The result is that emergency planning is less about carrying a large amount of physical cash and more about having multiple independent ways to access funds.
03 Why It Matters
Travel emergencies are expensive partly because they happen when you have the least bargaining power. A same-day hotel near an airport can cost far more than a room booked months earlier. A replacement train or flight can be priced at the current fare rather than the original fare. Medical clinics may require payment before treatment, depending on the country and provider.
Without a backup fund, travelers may rely on high-interest credit, cash advances or borrowing from family. Those options can solve the immediate problem but add long-term cost. A small emergency reserve can therefore protect both the trip and the household budget after returning home.
It also reduces decision pressure. When you know you can afford one extra night or a safe ride, you are less likely to make a risky choice simply because it is cheaper.
04 What It Means for You
Think about the most expensive plausible problem that could happen during your trip, not the most dramatic imaginable disaster. For a domestic weekend trip, the likely emergency may be an extra hotel night, replacement transport and meals. For an international trip, you may need enough room for a missed flight, urgent medical care, lost baggage essentials and temporary card problems.
Keep the emergency fund separate from the normal spending budget. If you mix it into your daily spending account, it is easy to spend it gradually and discover later that the reserve is gone.
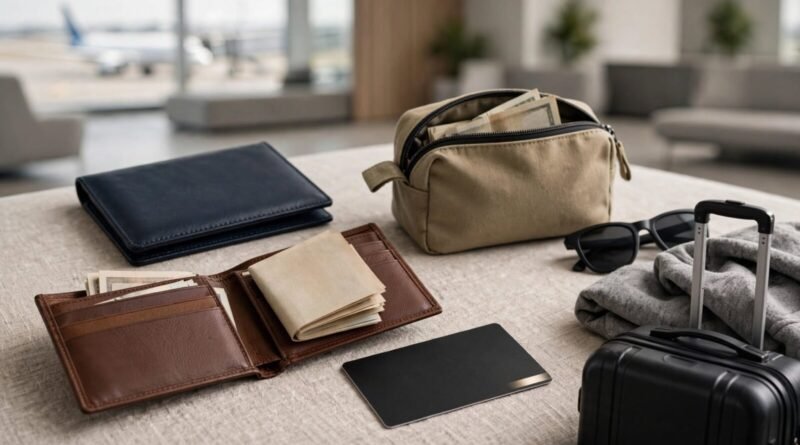
Use at least two access methods. One could be a primary credit card and another a debit card or backup credit card stored separately. A modest amount of local cash can help if cards fail, but carrying your entire emergency reserve in cash creates theft risk.
Also know your insurance. Travel insurance may cover specific disruptions, but exclusions, deductibles and documentation requirements matter. The emergency fund should be able to bridge the gap until a claim is resolved.
05 Numbers + Context
A simple starting framework is to estimate one day of unavoidable extra costs. Suppose an unexpected delay could require a $180 hotel, $60 in meals and local transport, and a $250 replacement ticket. That is already $490. Add basic replacement essentials or medication and the practical reserve may need to be $600 or more.
For a longer international trip, some travelers may prefer a reserve equal to 10% to 20% of the total trip budget, while others may base it on the cost of getting home quickly. If the trip costs $3,000, a 15% reserve would be $450. If a last-minute flight home could cost $900, then the return-flight risk may be the more useful benchmark.
The right number depends on destination, trip length, insurance coverage, available credit and personal risk tolerance. A traveler with strong insurance, several cards and a large unused credit limit may need less cash on hand than someone traveling with one debit card and no insurance.
Do not count your entire available credit limit as an emergency fund if using it would create a balance you cannot repay. Access to debt is not the same as having a financial reserve.
06 Earnyx Takeaway
An emergency travel fund is not wasted money just because nothing goes wrong. Its value comes from the options it gives you when something does. The goal is not to overfund every possible disaster. It is to cover the most realistic disruption without depending on expensive borrowing.
The Earnyx approach is to size the reserve around one meaningful emergency, keep it separate from normal spending and make sure you can access it in more than one way. If you return home without touching it, that is not a failure. It means the buffer did its job by giving you protection without becoming part of the vacation budget.
Know what your trip is really worth by including the cost of being able to handle the unexpected.
One more practical test is accessibility. An emergency fund that exists only in an account you cannot reach abroad is not fully useful. Before departure, confirm card PINs, bank contact numbers, app access and any travel-notice requirements. Store critical account details securely rather than depending on one phone.
For couples or families, divide backup access between travelers. If one wallet, phone or bag disappears, the group should still have another working payment method. This redundancy is often more valuable than simply increasing the total amount of emergency money.