Monthly Checking Account Fees: When a “Simple” Bank Account Costs More Than It Looks
Table of Contents
01 Event
Checking accounts are often treated as basic financial infrastructure, so a monthly maintenance fee can feel small enough to ignore. But recurring bank fees deserve the same scrutiny as any other subscription because they continue whether you actively think about them or not.
02 What Changed?
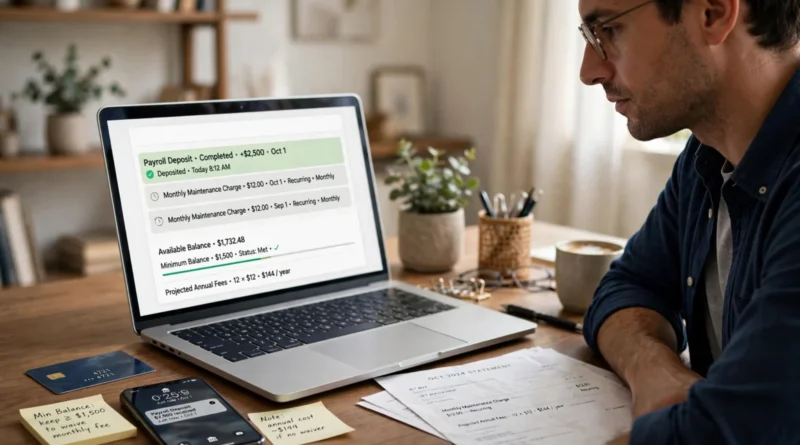
Many checking accounts waive the monthly fee if you meet specific conditions such as maintaining a minimum balance, receiving qualifying direct deposits, holding another account with the institution, or meeting age or student criteria. The complication is that the account may be “free” only when your behavior consistently matches the waiver rules.
That means the real cost is not simply the posted monthly fee. It is the probability that you will actually qualify for the waiver every month.
03 Why It Matters
A $12 monthly fee equals $144 per year. Over five years, that is $720 before considering any other account charges. A customer who misses the waiver condition only four months per year still pays $48 annually for an account they may think of as free.
Monthly service charges also matter when comparing banks. A slightly higher savings rate, branch convenience, or sign-up incentive may not compensate for recurring checking fees.
04 What It Means for You
Read the account’s fee schedule and identify the exact waiver rule. Then ask whether that rule fits your normal financial life without forcing you to keep excess cash idle or route income in an inconvenient way.
If direct deposit waives the fee and you already receive payroll that way, the account may effectively cost nothing. If the waiver requires a balance you routinely fall below, a no-fee account elsewhere may be a better fit.
05 Numbers + Context
The FDIC notes that some banks allow customers to avoid monthly maintenance fees through direct deposit and recommends asking whether other account fees can also be waived. The CFPB also distinguishes truly “free” checking from accounts that still impose monthly service charges.
References: FDIC — Overdraft and Account Fees; CFPB — What “Free” Checking Means.
06 Earnyx Takeaway
Do not judge a checking account by the monthly fee alone. Judge it by your expected annual fee after realistic waiver behavior. The best account is the one whose fee structure matches how you already get paid, save, and spend—not the one that looks cheapest under ideal conditions you rarely meet.