China Is Injecting $54 Billion Into Banks and Insurers — Why Beijing Wants More Financial Firepower
Table of Contents
01 Event
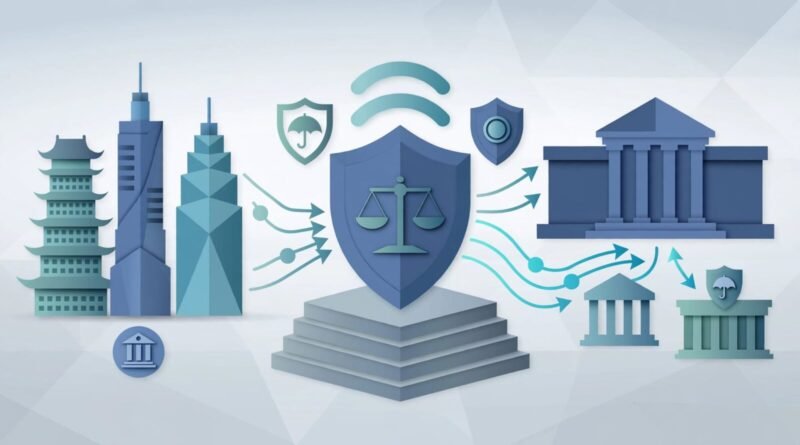
China is preparing a coordinated capital injection worth about $54 billion into major state-owned banks and insurers, according to company announcements reported by Reuters on September 6. The effort is designed to strengthen balance sheets across parts of the financial system as weak loan demand, low interest rates and pressure on profitability test both banks and insurance companies.
The package is not a single transfer to one institution. Reuters reported that three state lenders are set to receive a combined 290 billion yuan, while several state-owned insurers will receive additional capital from the Ministry of Finance or raise funds through private share placements.
Agricultural Bank of China plans to raise up to 160 billion yuan. Industrial and Commercial Bank of China plans to raise 100 billion yuan. Export-Import Bank of China is set to receive 30 billion yuan. On the insurance side, China Life Insurance Group will receive 35 billion yuan, China Taiping Insurance Group 7 billion yuan, China Export and Credit Insurance Corporation 10 billion yuan, while China Reinsurance Group plans to raise 3 billion yuan. People’s Insurance Company of China also plans to raise up to 15 billion yuan through a private placement to the Ministry of Finance.
The scale matters because China relies heavily on large state-controlled financial institutions to support credit growth, infrastructure financing, industrial policy and financial-market stability. More capital gives these institutions a bigger cushion against losses and can increase their capacity to lend or invest.
02 What Changed?
The important change is that Beijing is moving from broad support for the financial system to a concrete recapitalization across several major institutions. Capital injections are not the same as emergency liquidity. They strengthen the equity base of the institutions themselves, improving their ability to absorb losses and support additional assets.
For banks, the focus includes core Tier 1 capital, one of the highest-quality forms of regulatory capital. Stronger core capital can help banks expand lending while staying within prudential requirements. That is especially useful when policymakers want credit to remain available even as bank margins are under pressure.
China’s banks face an awkward combination of policy expectations and commercial constraints. Authorities want them to lend in support of economic growth, but weak credit demand and lower lending rates can reduce profitability. If a bank has to support more lending while earning less on the spread between loans and funding, additional capital provides breathing room.
Insurers face a different version of the problem. Insurance companies make long-term promises to policyholders and invest premiums to support those liabilities. Low interest rates reduce the returns available on bonds and other conservative investments. If expected investment returns fall while liabilities remain, solvency pressure can rise.
Reuters reported that the package is also intended to help large financial institutions support longer-term stock-market objectives and manage higher-risk peers. That means Beijing is not only strengthening individual firms; it is increasing the system’s capacity to act as a stabilizing policy tool.
03 Why It Matters
Bank capital is the financial system’s shock absorber. A better-capitalized bank can absorb more losses without immediately shrinking lending or threatening depositors. It also has more room to hold assets under regulatory capital rules.
That matters for China because policymakers are trying to prevent financial weakness from becoming another drag on an economy already dealing with soft demand in several sectors. If banks become too cautious, credit growth can weaken further, reinforcing slower business investment and consumer spending.
Insurer capital matters because policyholders depend on insurers making good on promises years into the future. Stronger solvency buffers help insurers withstand investment volatility, low yields and unexpected claims without being forced into aggressive asset sales.
The move also has global implications. China is the world’s second-largest economy. Changes in Chinese lending can affect commodity demand, infrastructure spending, industrial production, property activity and imports. A stronger banking system does not guarantee faster growth, but it reduces the chance that financial-sector stress becomes an additional source of weakness.
Investors should avoid reading the $54 billion headline as automatic evidence of a banking crisis. Governments recapitalize strategic financial institutions for many reasons, including preventive strengthening. The better question is why policymakers believe more capital is useful now.
04 What It Means for You
For an ordinary consumer outside China, a bank recapitalization may look remote. The connection becomes clearer when you follow the chain. More bank capital can preserve lending capacity. More lending can support business investment, infrastructure, housing activity or consumption. Those activities affect imports, commodity demand, factory orders and financial markets around the world.
For Chinese borrowers, stronger bank capital can help ensure banks have room to lend, but it does not automatically create demand. A company will not borrow simply because a bank has more equity if the company sees weak customer demand or poor expected returns from a new investment.
That distinction is critical. Recapitalizing the supply side of credit is easier than creating healthy demand for credit. Beijing can strengthen a bank’s balance sheet, but it cannot force every household or company to view new borrowing as worthwhile.
For investors in banks or insurers, the capital injection can be positive for resilience but may also dilute existing shareholders when new shares are issued. The exact effect depends on the structure and pricing of each transaction.
For policy watchers, the package is a signal that Beijing wants its financial institutions ready to carry more weight. That may include lending support, market stabilization and absorbing stress elsewhere in the system.
05 Numbers + Context
The banking side of the package totals 290 billion yuan across three institutions. Agricultural Bank of China accounts for 160 billion yuan, ICBC for 100 billion yuan and Export-Import Bank of China for 30 billion yuan. Reuters converted the bank total to roughly $43 billion.
On the insurance side, the announced or planned amounts include 35 billion yuan for China Life, 7 billion yuan for China Taiping, 10 billion yuan for China Export and Credit Insurance, 3 billion yuan for China Reinsurance, and up to 15 billion yuan through PICC’s planned placement.
Together, the package is around $54 billion at the exchange rates used in Reuters’ reporting. That is a large headline number, but context matters: the money is spread across several institutions, including some of the largest banks in the world by assets.
Capital also does not turn into consumer loans on a one-for-one basis. A 1 yuan increase in regulatory capital can support multiple yuan of assets depending on risk weights, capital requirements and the composition of the bank’s balance sheet. How much new lending actually appears therefore depends on loan demand, credit standards, asset quality and management decisions.
The same caution applies to insurers. A capital injection improves solvency headroom, but it does not eliminate investment risk or guarantee higher returns. It simply increases the financial buffer available to manage those risks.
06 Earnyx Takeaway
The $54 billion headline is best understood as Beijing buying more financial resilience and policy flexibility.
China wants its biggest banks strong enough to keep supporting credit even as profitability is pressured. It wants insurers able to handle low-rate conditions and market volatility. And it wants to reduce the chance that financial-sector weakness becomes a second problem layered on top of already-soft economic demand.
The trade-off is that recapitalization can strengthen institutions without solving the underlying reason households and businesses may be reluctant to borrow. If the core problem is weak confidence, property stress or poor expected returns on investment, stronger banks alone cannot manufacture healthy growth.
That is the real test to watch after the capital arrives. Does lending expand because businesses and households see worthwhile opportunities, or because banks are being encouraged to push more credit into weak demand?
For readers, the important lesson is that bank recapitalization is usually about capacity, not guaranteed outcomes. More capital makes the financial system better prepared to absorb risk. Whether that turns into stronger economic growth depends on what borrowers do with the credit capacity that becomes available.
Source: Reuters, September 6, 2026, based on Ministry of Finance and company announcements.