Banks Line Up $22 Billion for Blackstone-Alphabet AI Cloud Venture
The artificial-intelligence infrastructure boom is increasingly being financed with enormous pools of debt as investors race to build the computing capacity required for advanced models.
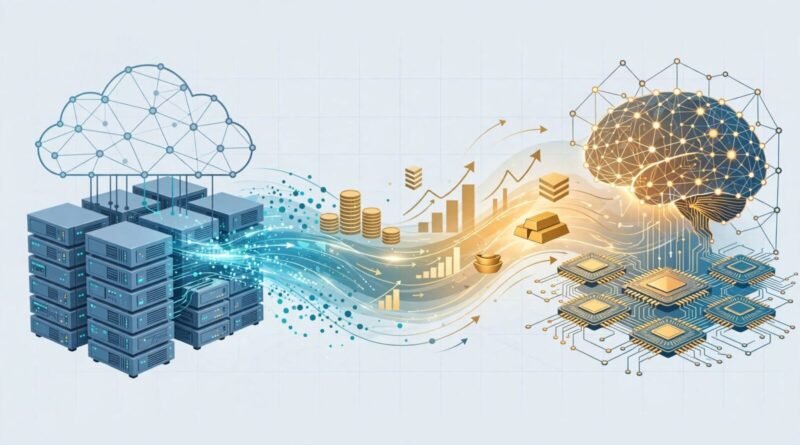
Reuters reported that banks are providing roughly $22 billion in financing connected with Crux AI, a cloud venture involving Blackstone and Alphabet. The scale of the financing illustrates how the AI boom is expanding beyond venture capital and technology-company cash budgets into the global credit markets.
For investors and consumers, the story matters because data centers and AI chips require extraordinary upfront capital. The returns on that investment depend on whether future demand for computing is large and durable enough to support the debt being accumulated today.
Table of Contents
Why AI infrastructure costs so much
Advanced AI models require large clusters of specialized processors, high-speed networking, storage and power infrastructure. Those systems are housed in data centers that also need land, cooling, backup power and connections to electricity grids.
The chips themselves can be expensive, but hardware is only one component. Constructing facilities, securing power capacity and maintaining computing equipment can push project costs into the billions.
This means the AI investment cycle resembles other capital-intensive industries more than a traditional software startup. A software company can sometimes scale by adding relatively inexpensive cloud capacity. A major AI infrastructure provider may need to commit billions before customer revenue fully materializes.
Debt is becoming part of the AI story
Much of the early AI boom was discussed through equity valuations: how much startups were worth, how much technology stocks gained and how much venture capital flowed into model developers.
Large-scale debt financing changes the risk profile. Equity investors absorb losses if a project disappoints, while lenders expect contractual interest and principal payments. Projects therefore need dependable cash flows or strong sponsors to support large debt packages.
For banks, AI infrastructure can create lucrative lending opportunities. It also creates concentration risk if many institutions finance similar projects based on the same assumptions about future computing demand.
Why Blackstone and Alphabet matter
Large infrastructure investors bring experience financing long-lived physical assets, while major technology companies bring cloud expertise and potential demand. Combining those capabilities can make projects more financeable than standalone speculative developments.
Still, the economics depend on contract structure. Long-term customer commitments can reduce risk because they provide predictable revenue. Facilities built without sufficient contracted demand are more exposed to changing technology prices and utilization.
The rapid evolution of AI chips adds another complication: expensive hardware can become less competitive when newer processors deliver substantially better performance or energy efficiency.
The hidden constraint is electricity
AI data centers consume large amounts of electricity, and access to power is becoming a major bottleneck in some markets. Building a facility is not enough if the local grid cannot provide the required capacity.
Developers are therefore investing in substations, transmission connections and power-generation agreements alongside computing hardware. These infrastructure requirements lengthen development timelines and add cost.
Earnyx has been following this physical side of AI through our coverage of AI hardware demand and factory activity. The $22 billion financing story adds another layer: the hardware boom increasingly depends on sophisticated financial engineering as well as semiconductor supply.
Why cloud demand is the key variable
The central investment question is utilization. A data center full of expensive AI accelerators only earns an attractive return if customers pay to use that capacity often enough and at sufficient prices.
Current demand is strong because technology companies, enterprises and AI laboratories are training and deploying increasingly capable systems. But investors must make assumptions about demand many years into the future when financing long-lived infrastructure.
If AI adoption continues expanding rapidly, today’s capacity could prove valuable. If computing becomes dramatically more efficient or demand growth slows, some projects could face weaker economics.
Falling compute prices can be both good and bad
Technology improvements tend to reduce the cost of computing per unit of performance. That can expand demand because applications that were previously too expensive become economical.
For infrastructure owners, however, rapidly improving chips can pressure the value of older hardware. A server purchased today may still work several years from now but could generate less revenue if customers prefer newer systems.
Successful operators therefore need to manage equipment refresh cycles, energy efficiency and customer contracts carefully.
What the financing says about AI confidence
Banks do not commit tens of billions of dollars without extensive due diligence, and the presence of major sponsors suggests significant institutional confidence in AI infrastructure demand.
That confidence should not be confused with certainty. Credit markets have financed investment booms before that later produced excess capacity. The relevant question is whether contracted revenue, asset value and sponsor support provide sufficient protection if demand develops differently from forecasts.
For investors, debt growth is therefore an indicator worth monitoring alongside technology-company capital expenditure.
Who ultimately pays for the infrastructure?
The cost of AI infrastructure eventually has to be supported by customers. That may happen through cloud-computing fees, enterprise software subscriptions, advertising revenue or productivity gains that make AI services worth paying for.
If end users resist higher prices, providers may face pressure to absorb infrastructure costs in their margins. Competition among cloud companies can intensify that pressure.
This is why the AI industry’s revenue model matters just as much as its technical progress. Enormous capital investment is easier to justify when customers generate measurable economic value from the computing they purchase.
The bigger picture
A $22 billion financing package is another sign that AI has become an infrastructure cycle, not simply a software trend. Banks, private-equity firms, utilities, construction companies and data-center developers are increasingly tied to the industry’s growth.
That broadens both the opportunity and the risk. If AI demand continues expanding, the economic benefits can spread through semiconductor manufacturing, energy and infrastructure. If expectations prove too optimistic, financial exposure will also be distributed more widely.
The next stage of the AI boom will therefore be judged not only by better models but by whether the enormous physical and financial investment behind them produces sustainable cash flow. The scale of the Crux financing shows how high those stakes have become.
Pingback: Spain Grid Expansion Targets Data Centers and Electrification
Pingback: AI Slowdown Fears Hit Nvidia and Tech Stocks