Coinsurance vs Copays: Why the Difference Can Change Your Medical Bill
Table of Contents
01 Event
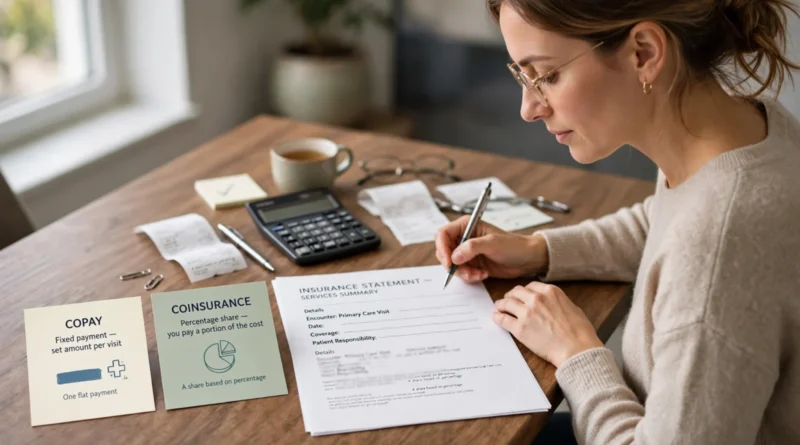
Health insurance cost sharing is full of terms that sound similar but behave very differently. Two of the most important are copays and coinsurance. A copay is generally a fixed dollar amount you pay for a covered service, while coinsurance is a percentage of the allowed cost that you pay after applicable deductible rules are satisfied. The distinction matters because a fixed $30 payment and a 20% share of a large medical bill can create dramatically different out-of-pocket costs.
02 What Changed?
Consumers increasingly need to evaluate more than the monthly premium. A plan can advertise affordable office-visit copays while using coinsurance for imaging, outpatient procedures, hospital services, specialty drugs, or other expensive care. Two plans with similar premiums can therefore create very different household costs once significant treatment is needed.
HealthCare.gov defines a copayment as a fixed amount for a covered service and coinsurance as a percentage of the allowed cost. That difference sounds technical, but it is really a difference between a relatively predictable expense and one that scales with the price of care.
03 Why It Matters
Copays are easier to budget. If your plan says a primary-care visit has a $30 copay, you can usually anticipate that expense, subject to the plan’s deductible and coverage rules. Coinsurance is variable because your share depends on the allowed amount. Twenty percent of $200 is $40; twenty percent of $5,000 is $1,000. This is why focusing only on familiar copays can understate the financial risk of expensive care.
Coinsurance can be especially important when you are comparing plans for a year in which you expect surgery, diagnostic imaging, specialist treatment, therapy, or costly prescriptions. A low premium can be offset by higher cost sharing if you actually use substantial care.
04 What It Means for You
When comparing health plans, identify which services use copays and which use coinsurance. Then look at the deductible and out-of-pocket maximum because those provisions interact with cost sharing. Pay particular attention to services you reasonably expect to use rather than comparing only routine office visits.
Also distinguish the provider’s billed charge from the plan’s negotiated or allowed amount. Coinsurance is typically calculated from the allowed amount for covered services, not necessarily the headline charge on the provider’s bill. Network status matters because in-network and out-of-network rules can differ materially.
For households choosing between plans, it can help to model three scenarios instead of one: a low-use year with mostly routine visits, a moderate-use year with specialists or imaging, and a high-use year involving hospitalization or a major procedure. A plan that looks cheapest in the first scenario may not remain cheapest in the second or third. This is why total-cost estimates are more useful than premium comparisons alone.
Finally, check whether the plan places some services outside the deductible or applies separate prescription-drug cost sharing. The same plan can use copays for one category and coinsurance for another.
05 Numbers + Context
Imagine Plan A charges a $50 specialist copay. Plan B requires 20% coinsurance after the deductible. For an allowed specialist service of $250, 20% equals $50, so the immediate cost can look identical. But if another covered service has an allowed amount of $2,500, 20% becomes $500. The percentage structure creates much wider variability.
HealthCare.gov gives a larger example: with $12,000 of allowed costs, a $3,000 deductible and 20% coinsurance, the consumer would pay the first $3,000 plus $1,800 of coinsurance on the remaining $9,000, for $4,800 total before reaching the plan’s out-of-pocket maximum. The point is not that this exact structure applies to every plan, but that percentage-based cost sharing can become significant quickly.
Reference: HealthCare.gov copayment definition, HealthCare.gov coinsurance guidance, and out-of-pocket maximum guidance.
06 Earnyx Takeaway
Copays buy predictability; coinsurance makes your cost move with the price of care. Neither is automatically better. Model the services you are most likely to use, then compare the premium, deductible, copays, coinsurance, network rules, and out-of-pocket ceiling together. The cheapest-looking monthly premium can lose its advantage quickly if the cost-sharing structure does not fit how you actually use healthcare.